Projects in Jebel Ali
View on map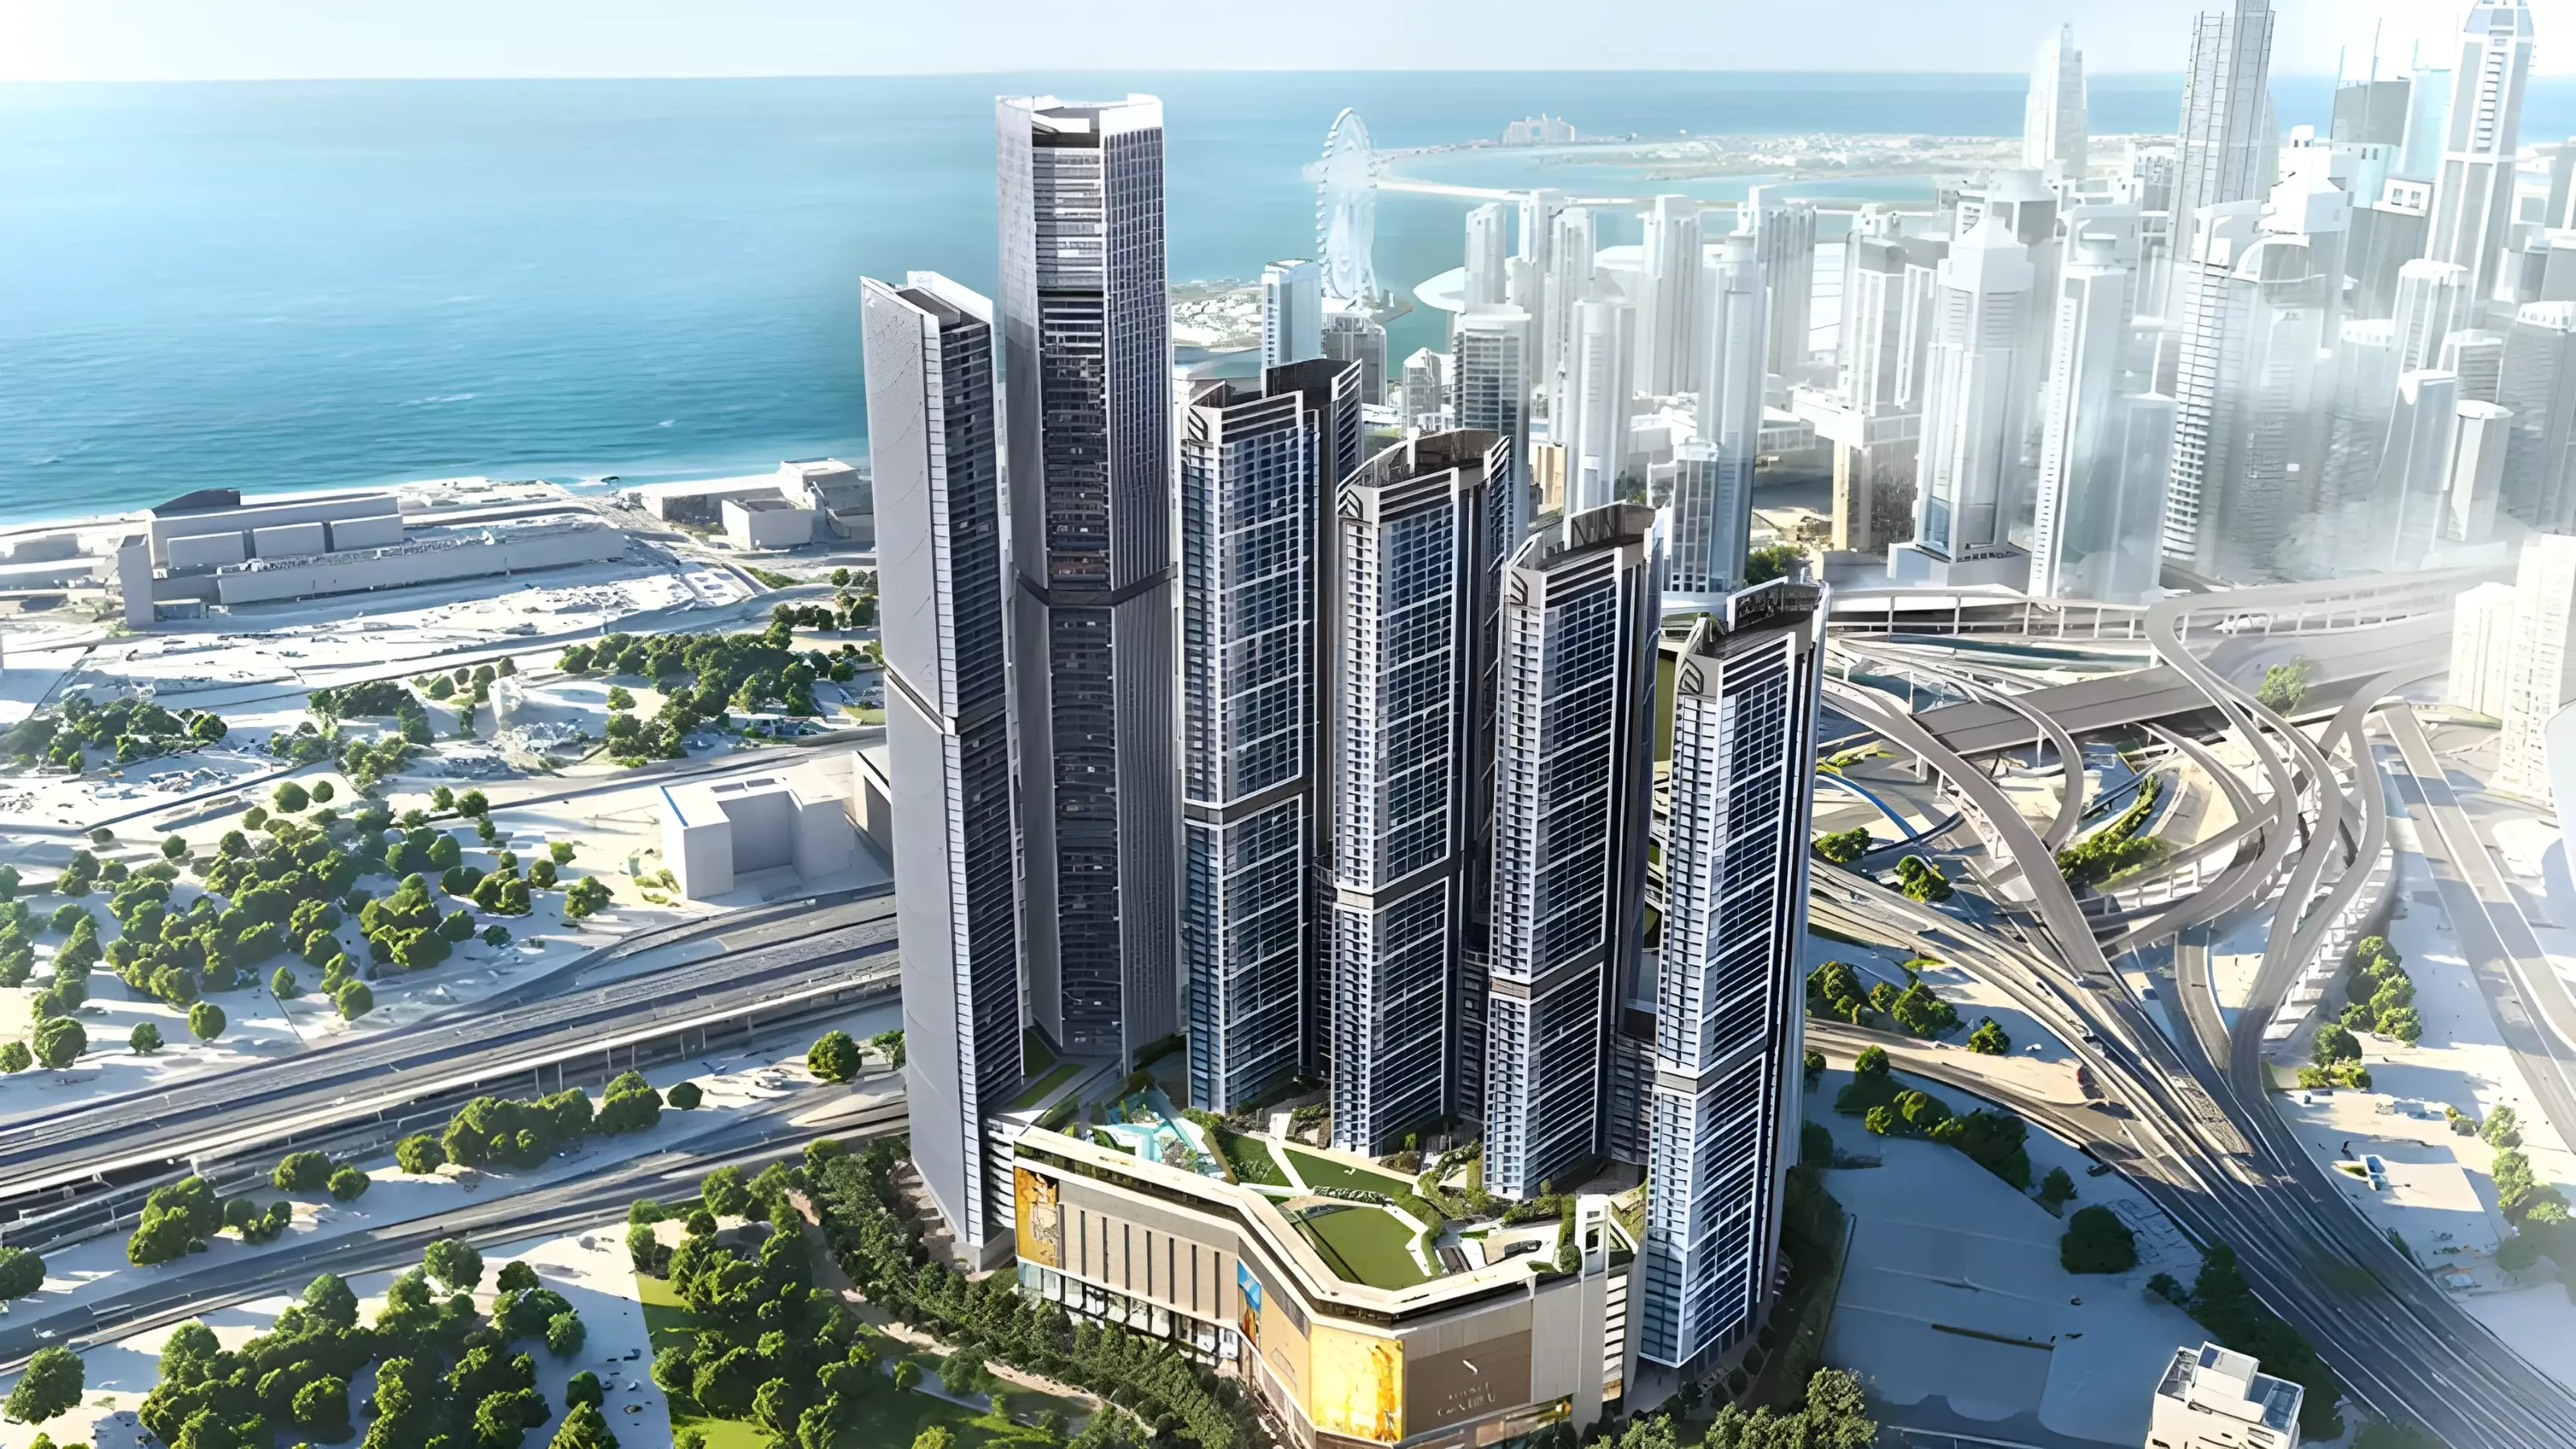
AED 1.6M
AED 564K

AED 1.7M
AED 1.4M
AED 570K
AED 1.5M
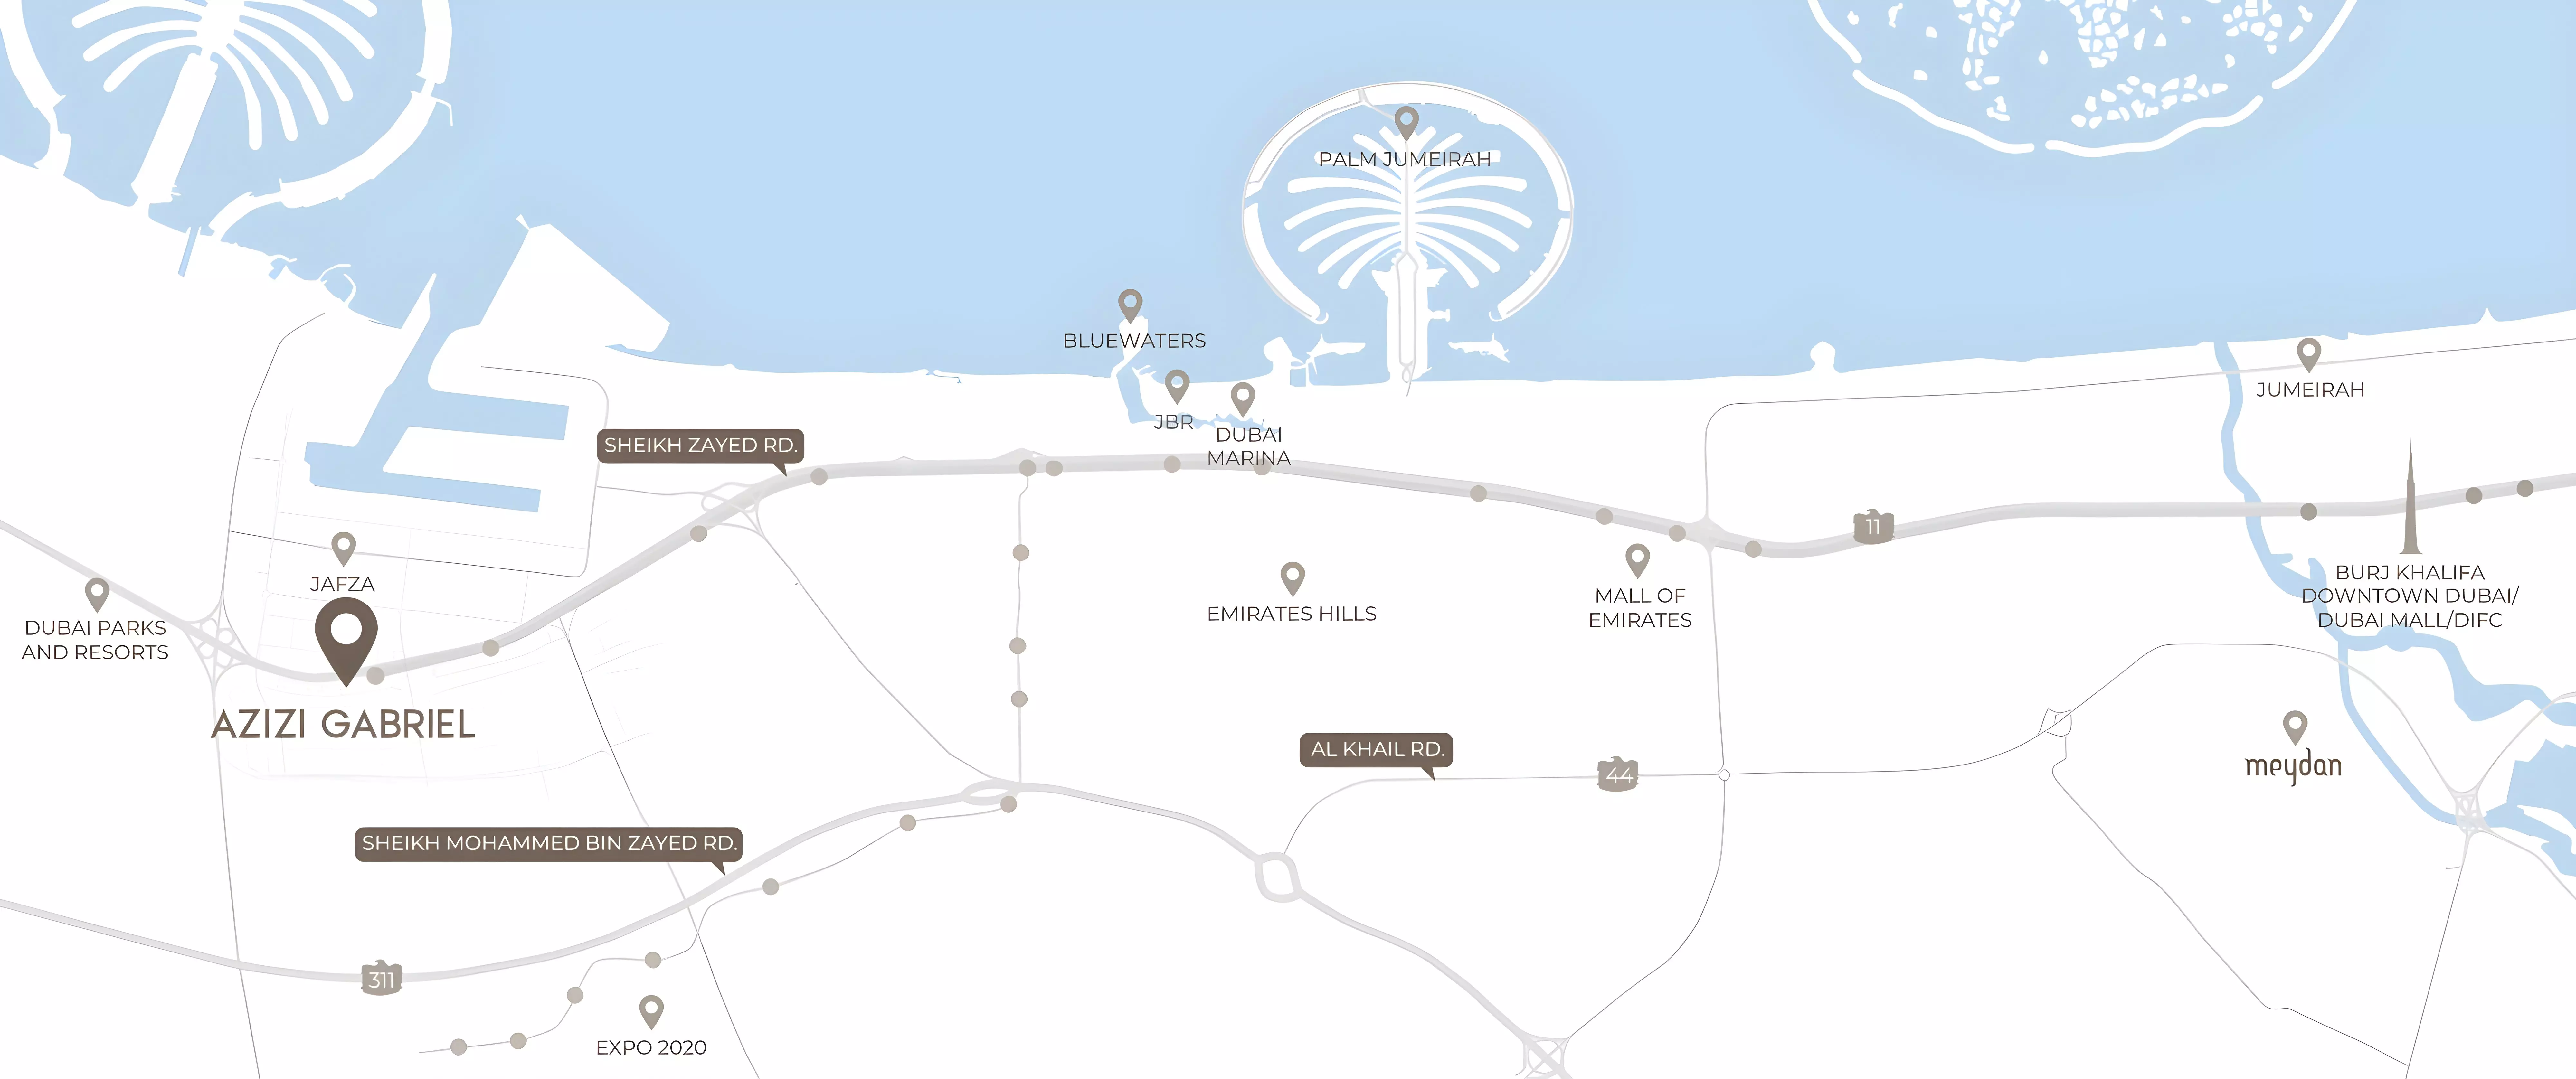
AED 564K
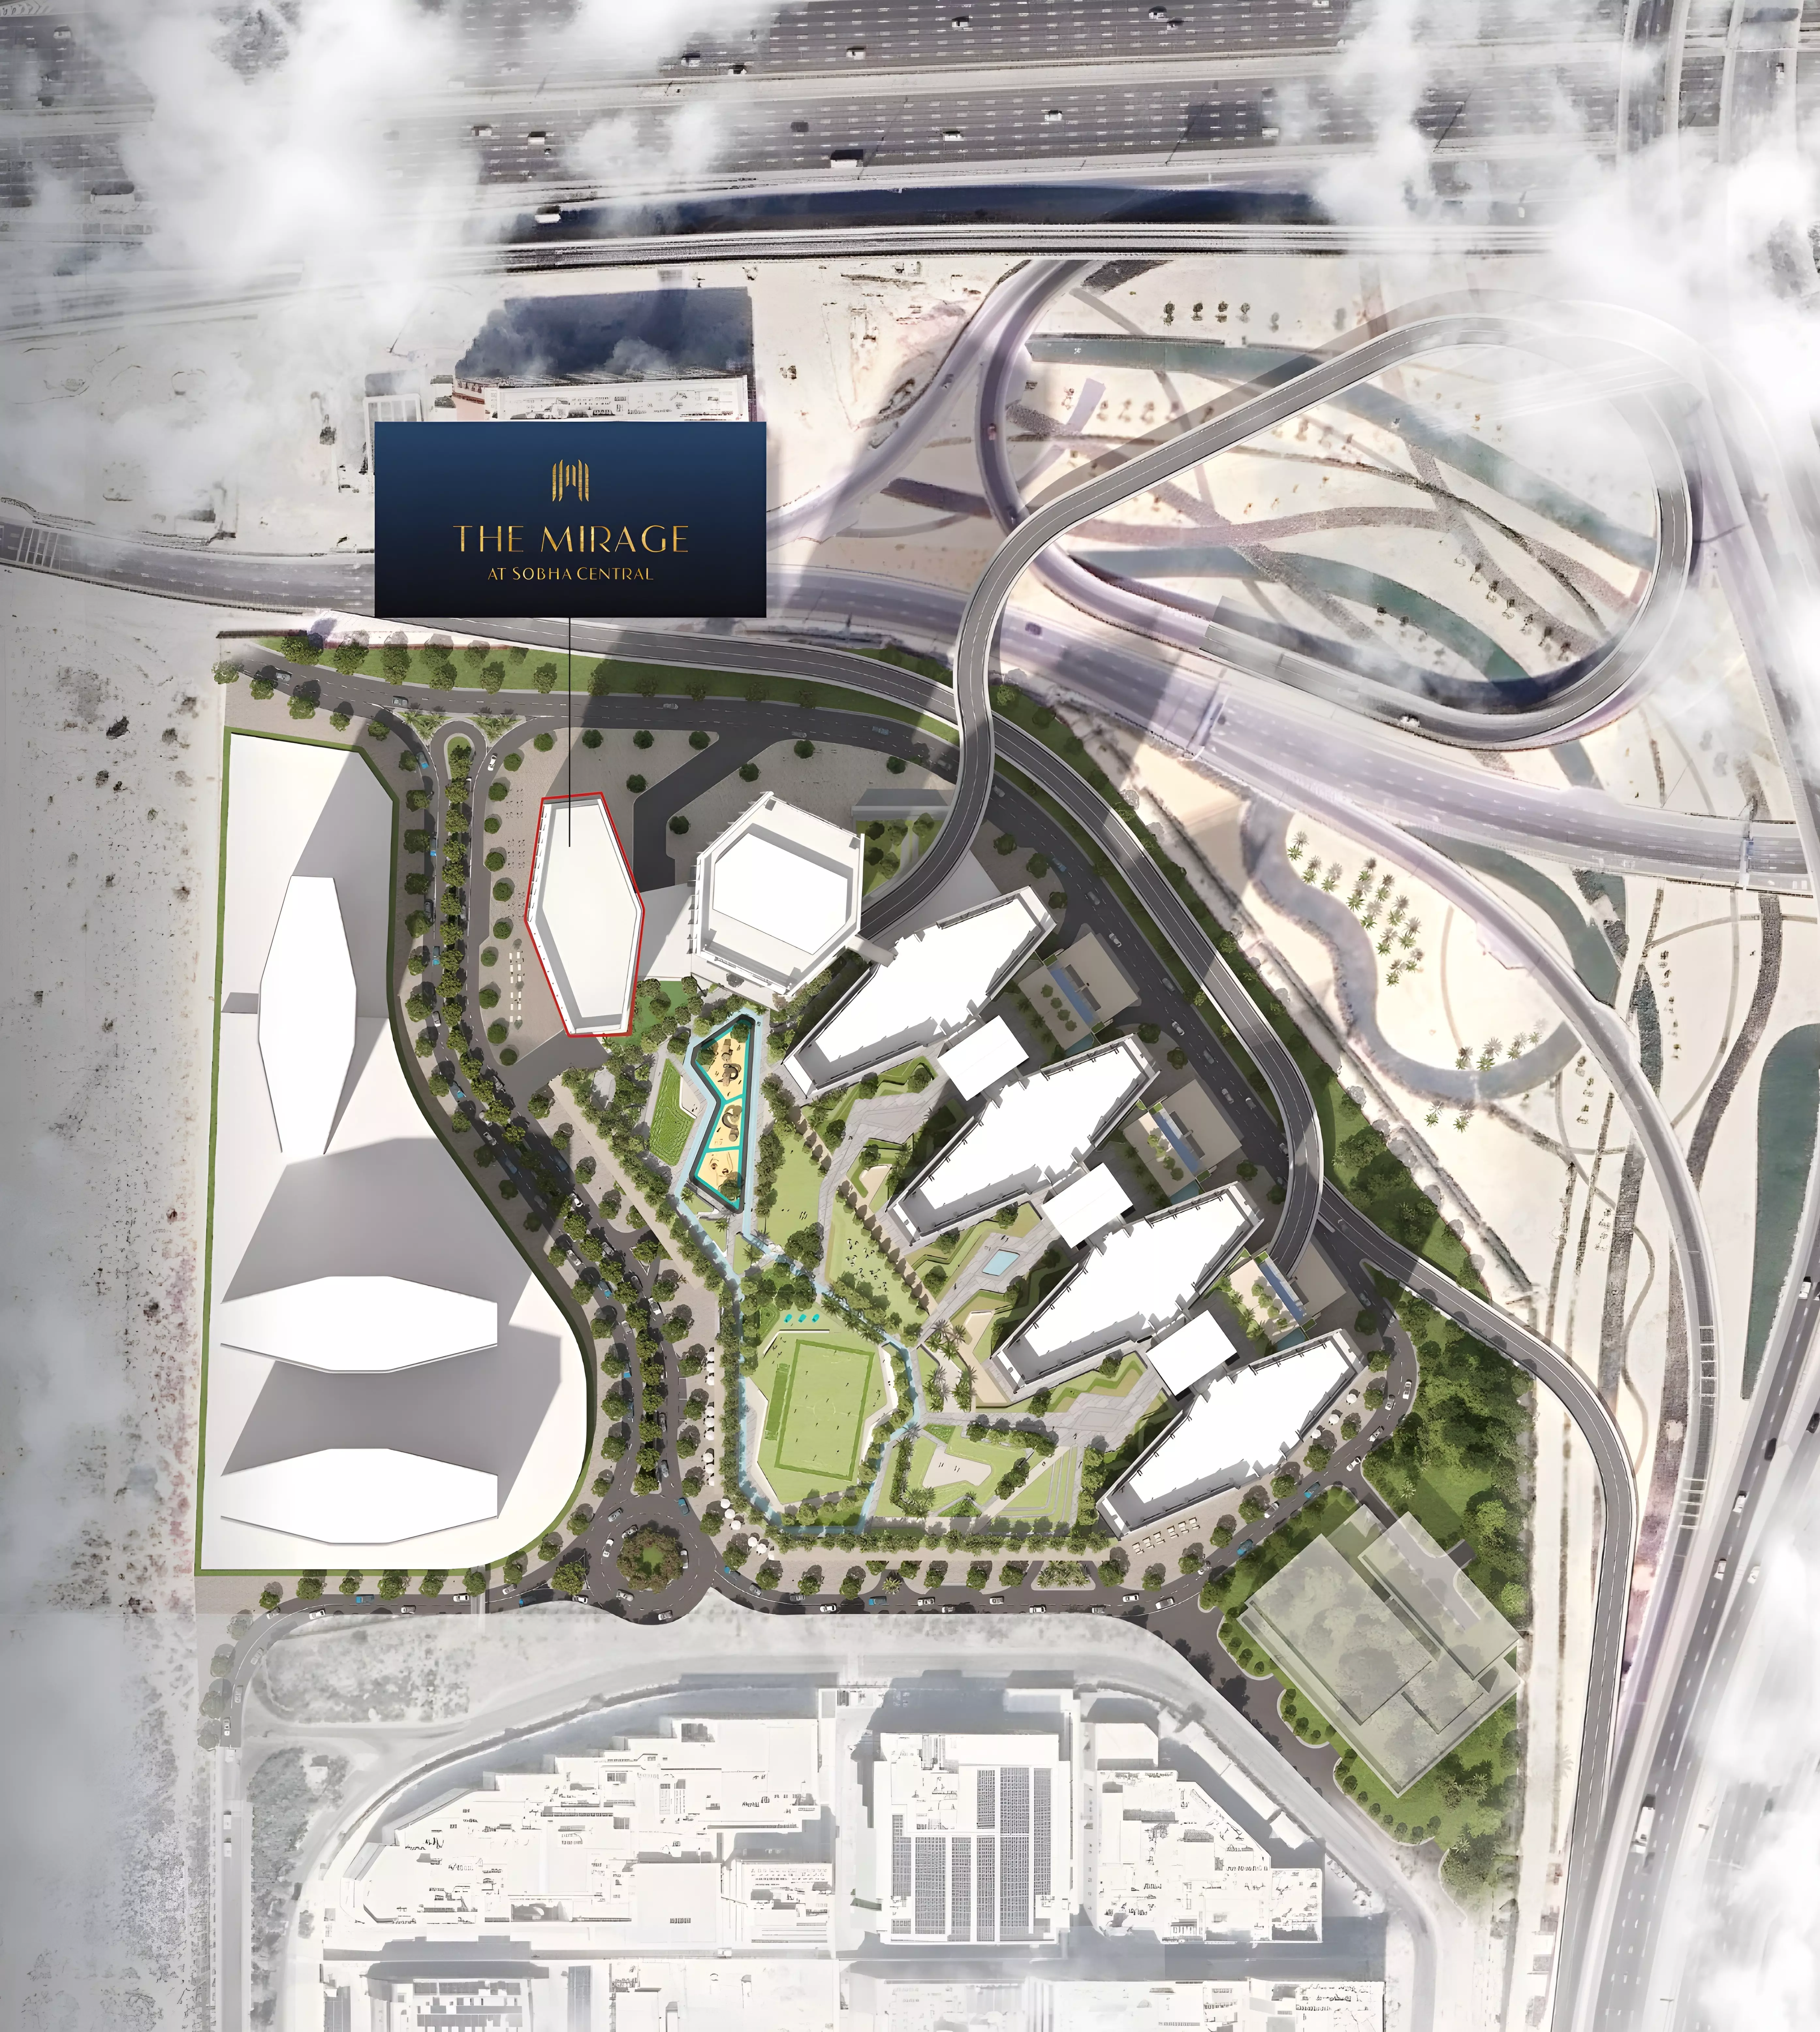
AED 2M
On request
AED 2.5M
Nearby Projects
- New Projects in Wasl Gate
- New Projects in Al Furjan
- New Projects in Jumeirah Park
- New Projects in Jumeirah Islands
- New Projects in Jumeirah Lake Towers
- New Projects in Jumeirah Beach Residence
- New Projects in Downtown Jebel Ali
- New Projects in Dubai Marina
- New Projects in Jumeirah Village Triangle
- New Projects in Expo City
- New Projects in Dubai Production City (IMPZ)
- New Projects in Dubai Harbour
- New Projects in Jumeirah Golf Estates
- New Projects in Dubai Internet City
- New Projects in Barsha Heights (Tecom)
Other Developers
- New Projects by Zaya
- New Projects by Sobha Realty
- New Projects by Nakheel
- New Projects by Azizi Developments
- New Projects by Samana Developers
- New Projects by Object 1
- New Projects by Deyaar Development
- New Projects by Empire Developments
- New Projects by Forum Group
- New Projects by RSG international
- New Projects by Refine Development
- New Projects by Green Horizon Development
- New Projects by AB Developers
- New Projects by Ocean Pearl Property Development
- New Projects by deerfield
Southwest Dubai's Expanding Residential Corridor: New Projects in Jebel Ali
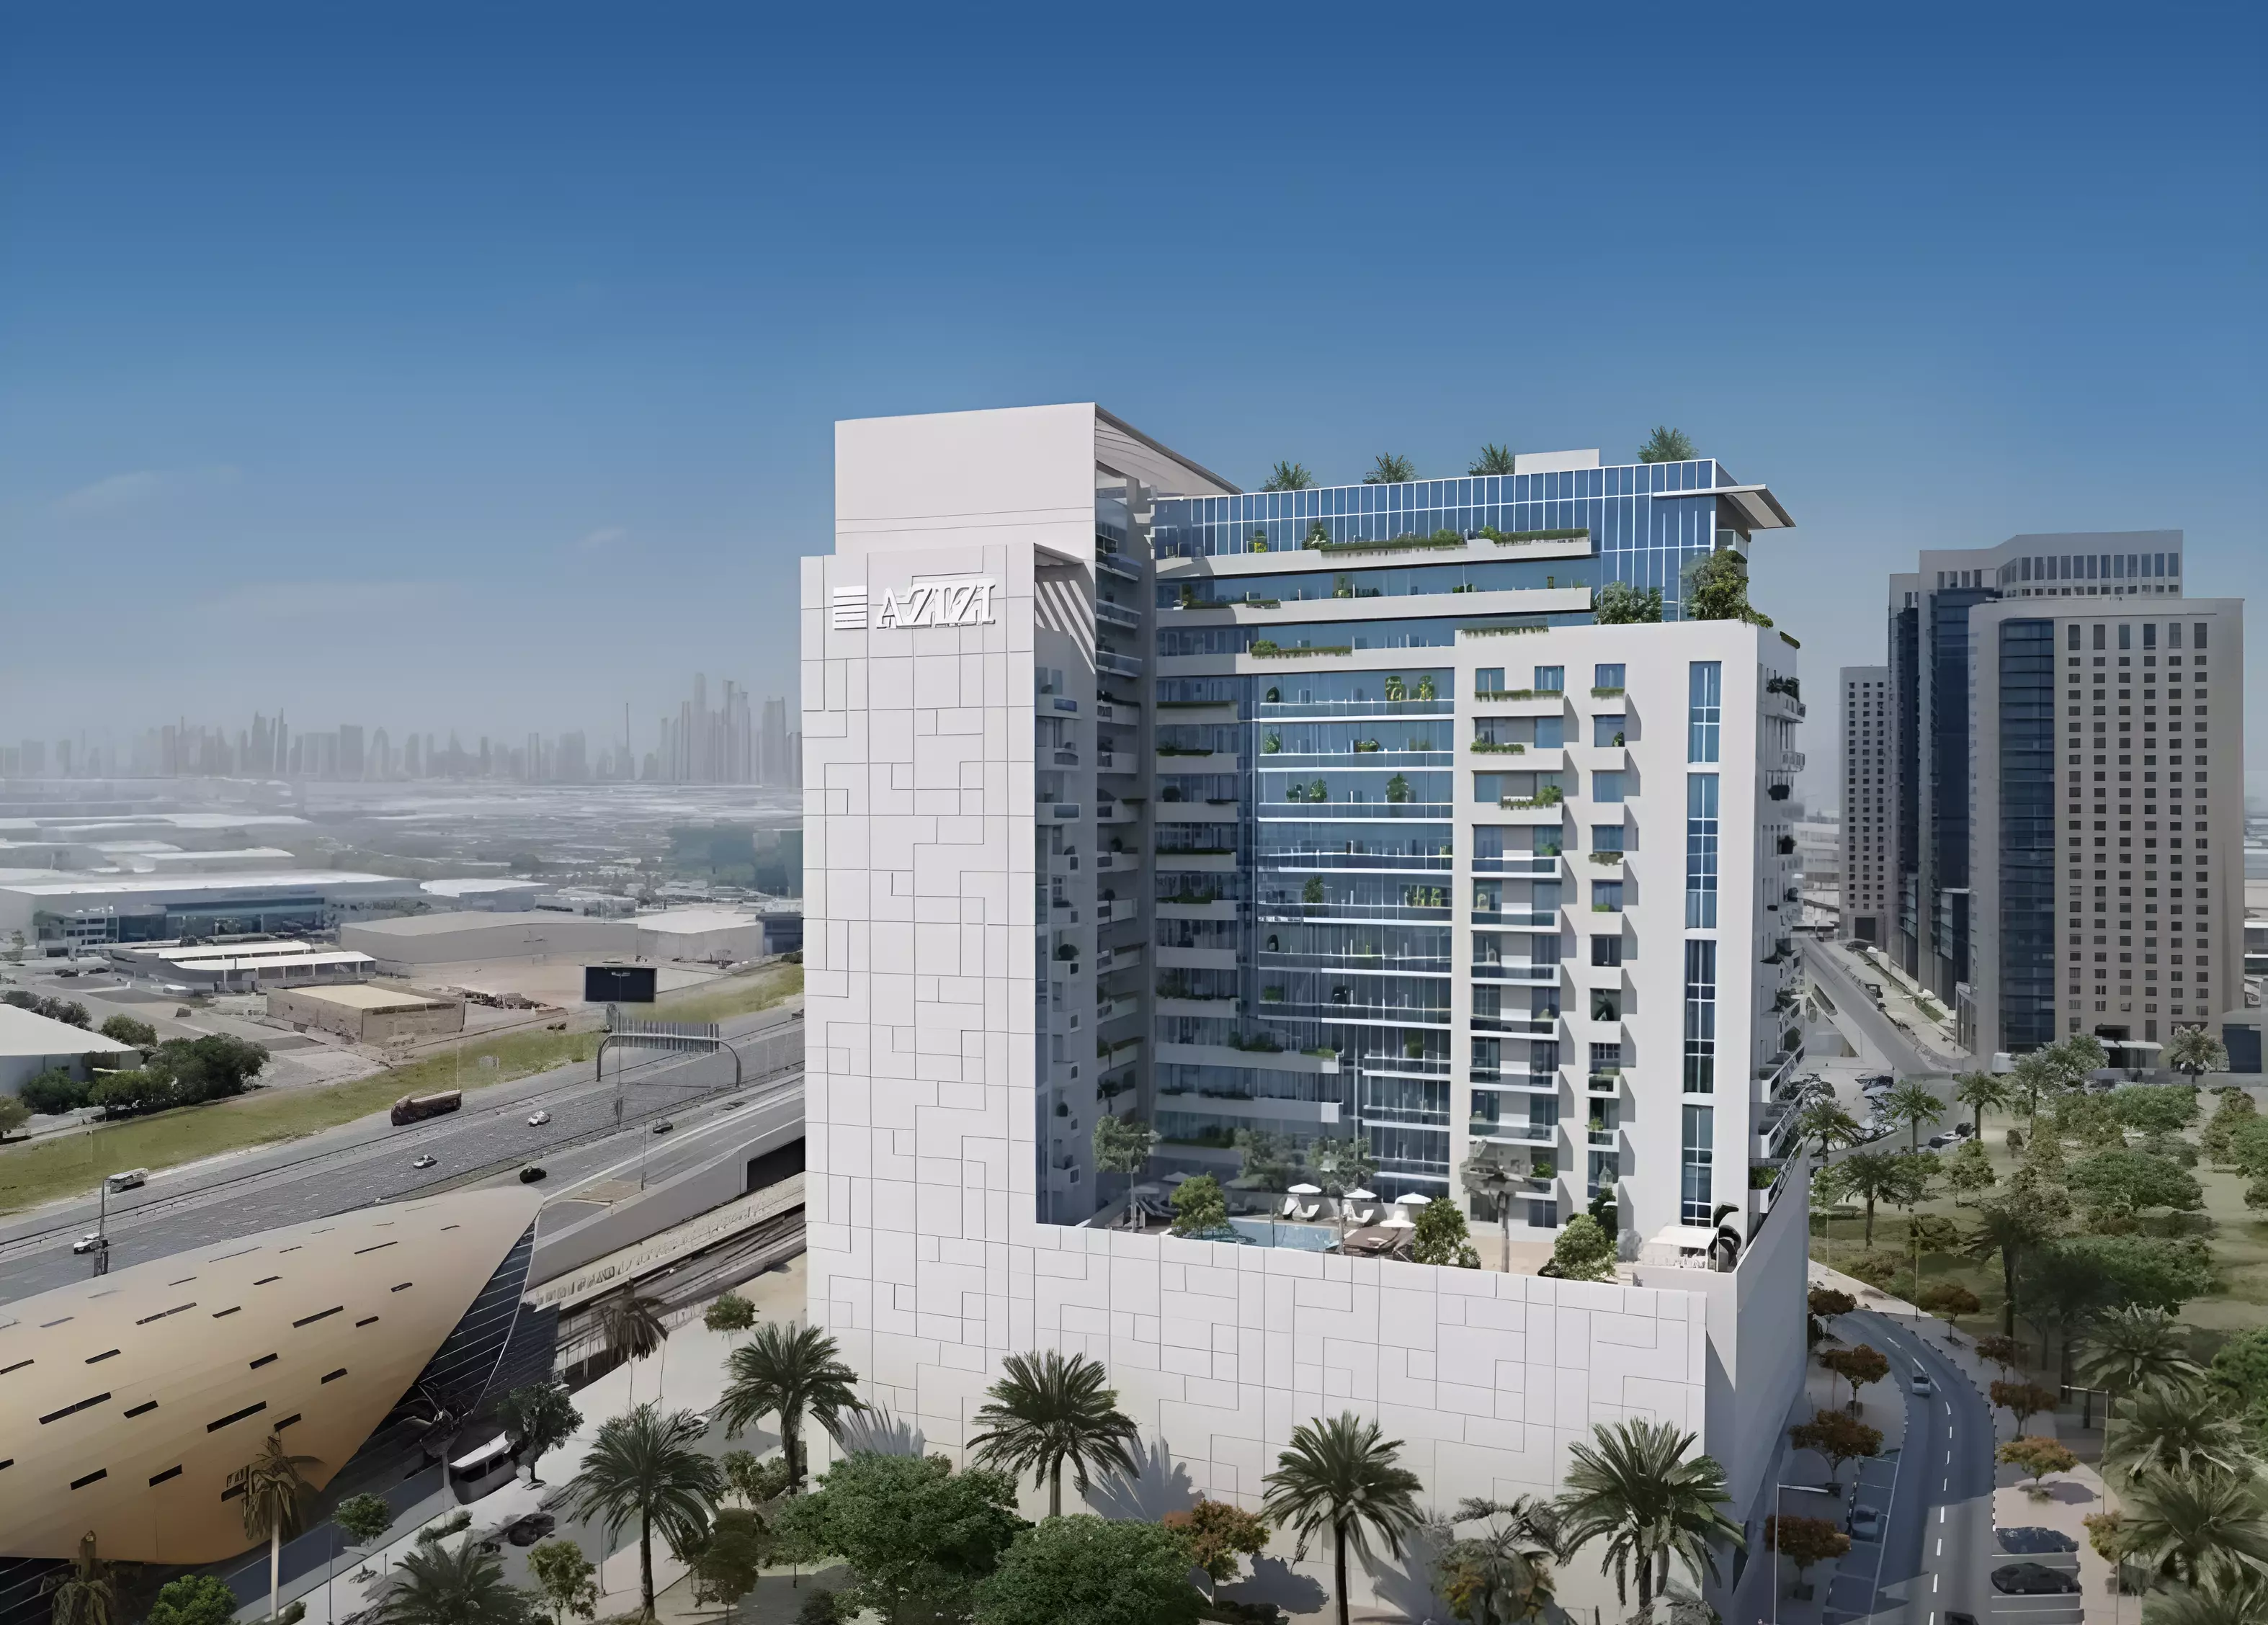
Jebel Ali occupies Dubai's southwestern corridor, historically defined by the port and free zone complex that anchors a significant share of the emirate's trade infrastructure. That industrial identity is giving way to a growing residential layer. With 36 active projects, the district now draws buyers across a range of sub-communities, each with its own character: Jebel Ali Hills carries villa-focused product, Jebel Ali Village has an established community feel, Sabah Square caters to mid-range apartment buyers, and Sobha Central represents the master-planned end of the spectrum. Knowing which pocket you are targeting matters here more than in districts with more uniform supply.
Where AED 1,635,000 Is the Midpoint
The median asking price across Jebel Ali's off-plan inventory is AED 1,635,000. That number anchors the middle of a range that runs from AED 527,250 at the floor to AED 16,500,000 at the ceiling. A spread that wide reflects the gap between compact apartments in high-density sub-communities and standalone villas in lower-density areas like Jebel Ali Hills. The two ends of the market are not in direct competition. Entry-level pricing draws investors working within tighter budgets; the upper range belongs to buyers seeking land title and space in a district that still offers it. The median is the most useful single number for a first-time buyer trying to calibrate expectations.
Apartments Lead, Villas Hold Real Weight
| Property Type | Projects |
|---|---|
| Apartment | 24 |
| Villa | 7 |
| Townhouse | 1 |
Apartments account for two-thirds of the project inventory, pointing to an investor-weighted buyer base and developers betting on rental demand in a corridor with strong employment infrastructure nearby. The villa count is not a token offering: 7 villa projects make Jebel Ali one of the few districts in Dubai's western belt where landed residential product is available at meaningful scale. That gives owner-occupiers a genuine alternative to apartment living without the price premium of more central villa districts. The single townhouse project sits between both categories and appeals to buyers who want private outdoor space without the land costs of a full villa.
15 Developers Across One District
15 developers are active across 36 projects, which means the market is fragmented without being dominated by a single name. Sobha Realty and Nakheel carry the deepest track records and typically the strongest resale liquidity in comparable Dubai sub-markets. Azizi Developments and Samana Developers are volume players with delivery histories across multiple locations. The remaining names, including Object 1, Deyaar Development, Forum Group, and others, make up a long tail of smaller launches.
Developer concentration shapes resale outcomes. Sobha Central functions as a master-planned community, with a single developer driving quality consistency and investor recognition, which tends to support secondary market activity. Projects by less established names will have thinner resale pools and require buyers to conduct more individual due diligence on delivery history and build standards.
From Units Already Complete to December 2030
The earliest completion date in Jebel Ali's active inventory is December 2023. That predates the current market by over two years, which means some projects listed here may already be built and handed over. Buyers considering those listings should verify current status directly, as the transaction may be a secondary sale or ready-unit transfer rather than a conventional off-plan purchase. The far end of the window runs to December 2030, giving buyers entering the market now an off-plan horizon of up to four years at the outer range.
Entry Costs and Post-Handover Structure
A minimum down payment of 3% is a notably low entry point. Most Dubai off-plan launches require between 10% and 20% at booking, so a 3% threshold changes the cash calculation for buyers managing liquidity across multiple commitments. 3 of the 36 projects include post-handover payment plans, which spread installments beyond the handover date and reduce the capital tied up during construction. That is a small share of the total inventory but the right one to identify if cash flow after keys is a constraint.
What the Amenity Mix Says About Residents
Children's Play Areas and Barbecue Areas sit alongside CCTV Security and Gymnasium provision at the top of the amenity frequency list. That pattern signals a resident profile weighted toward families and long-term occupiers rather than the short-stay rental buyer, who tends to prioritize concierge services and lap pools. The security emphasis, both CCTV and dedicated Security appearing among the most common features, reflects the district's positioning: developers are building gated community environments in an area that still borders industrial zones, and perimeter security is being marketed as a feature rather than treated as standard.